Built Around Your Operations
Start with what your company actually does and how it interacts with customers, contracts, and property.
START WITH THE BUSINESS
General Liability Insurance should start with what your company actually does, not with a generic policy description.
Whether you work at customer locations, welcome people onto your premises, sign contracts, or operate a growing business, our team can help you understand the liability coverage options relevant to your operation.
Prefer to talk? Call 281-697-6215.
Start with what your company actually does and how it interacts with customers, contracts, and property.
Understand available limits, exclusions, endorsements, and how General Liability fits into the broader insurance picture.
Relevant conversations for contractors, service businesses, offices, retailers, and other Texas companies.
A locally led agency helping business owners throughout the state.
UNDERSTAND THE OPERATION FIRST
A plumbing contractor does not operate like an accounting office.
A landscaping company does not operate like a restaurant.
A retailer does not operate like a technology company.
That is why the conversation should begin with the business itself.
The goal is not to make the process more complicated.
It is to make sure the insurance conversation reflects the business you are actually running.
COMMON REASONS TO START
A new company can create several commercial insurance questions at once.
Contracts may introduce insurance requirements that deserve review.
A request for evidence of coverage may trigger a new insurance conversation.
Contractors often encounter insurance requirements through customers, project agreements, or general contractors.
A lease may introduce insurance requirements that did not apply before.
New employees, customers, locations, revenue, or services can create reasons to revisit coverage.
UNDERSTAND THE BASICS
Exact protection depends on the policy, business, carrier, underwriting, limits, endorsements, exclusions, and conditions.
General Liability Insurance is a core commercial liability conversation for many businesses, but exact protection depends on the policy terms and limits.
Knowing that you have liability coverage is different from understanding how much protection you selected.
Deductibles may apply depending on the policy and coverage involved. Exact options vary.
Policies can include exclusions, conditions, and optional endorsements. Understanding what the specific policy says matters.
“I have General Liability Insurance” is not the same as “I understand what my policy actually covers.”
UNDERSTAND THE DIFFERENCE
A core commercial liability coverage conversation focused on certain business liability exposures.
A BOP may combine certain commercial coverages into one package for eligible small and midsize businesses.
The right option depends on the business, operations, property, carrier eligibility, coverage needs, and underwriting.
Explore Business Owner’s Policy InsuranceA STRONG FIT FOR MANY CONTRACTORS
Contractors often work at customer homes, commercial properties, job sites, and alongside other businesses.
General Liability may be one important part of a broader Contractor Insurance conversation.
Contractor insurance may also involve Commercial Auto, Commercial Property, tools and equipment, Workers’ Compensation considerations, BOP eligibility, and other Business Insurance depending on the operation.
WHEN A CONTRACT BRINGS YOU HERE
Insurance requirements often appear in contracts.
But not every contract asks for the same thing.
NEW COVERAGE OR EXISTING SERVICE?
If you do not currently have the requested coverage, start with our Business Insurance team.
If you already have Business Insurance with us and need help with a Certificate of Insurance, our service team can assist.
Request a Certificate or ServiceKeeping these two paths separate helps new sales inquiries and existing-customer service requests reach the right team.
MINIMUM REQUIREMENTS ARE NOT THE WHOLE PICTURE
A contract may establish a minimum insurance requirement. That requirement matters. But it does not automatically answer every question about the company’s broader risk.
Specific insurance requirements tied to one agreement.
Customers, locations, vehicles, property, employees, equipment, operations, and other contracts.
The goal is not to sell more insurance simply because more coverage exists.
It is to understand the difference between meeting a contract requirement and understanding the broader business.
WHAT CAN AFFECT THE PRICE?
There is no universal General Liability Insurance premium for every Texas business.
What the company actually does matters.
Different industries can create different underwriting considerations.
Business history may be relevant.
Revenue may be considered depending on the business and carrier.
Staffing and payroll may be relevant to underwriting.
Previous losses may affect eligibility or pricing.
Where the company operates can matter.
Selected limits may influence premium.
Where applicable, deductible choices may affect pricing.
Final eligibility, availability, pricing, and policy terms depend on carrier underwriting.
An accurate General Liability quote starts with understanding the business, not guessing at a price.
UNDERSTAND WHAT YOU ARE BUYING
A contract may start the conversation, but understanding the coverage matters too.
Know what limits you selected and why.
Vehicles, property, employees, equipment, and other exposures may require separate conversations.
New services, employees, locations, revenue, and contracts can create reasons to revisit coverage.
Personal and Business Insurance serve different purposes. Ask specifically.
GENERAL LIABILITY IS ONE PART OF THE PICTURE
Workers’ Compensation and Commercial Umbrella may also deserve discussion depending on the business and available options.
DIFFERENT BUSINESSES. DIFFERENT RISKS.
BUSINESS-OWNER EXPERIENCE
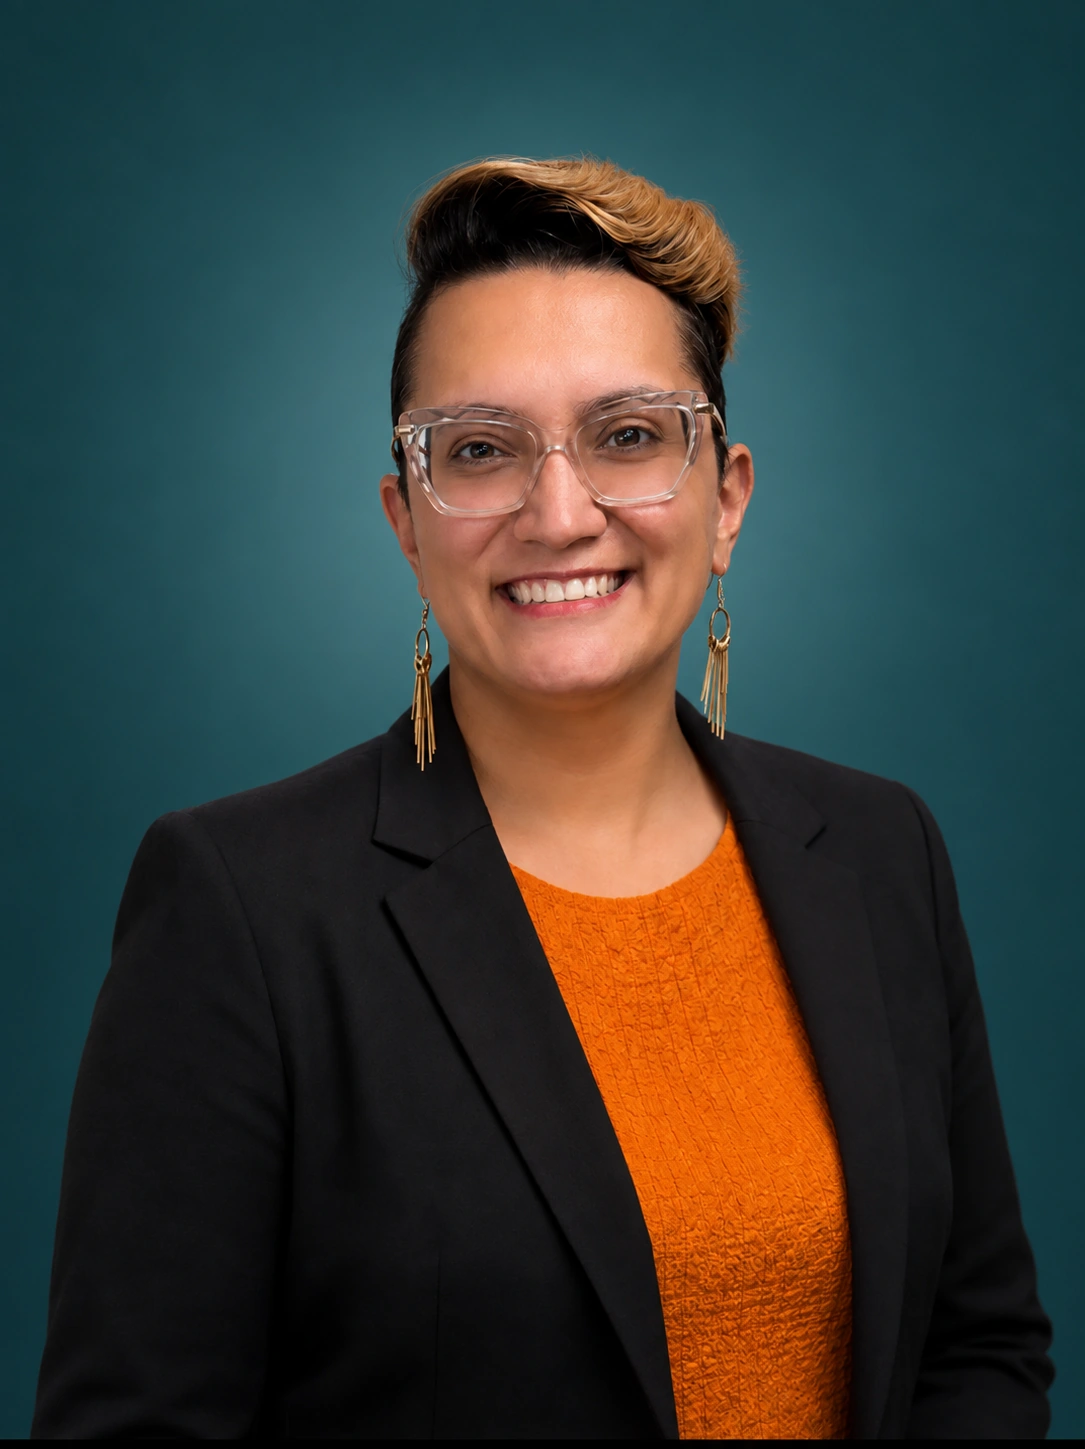
Agency Owner | Business Insurance & Operations
Francisco spent 15 years as a business owner in the trucking industry before helping lead Echevarria Agency.
He understands that behind an insurance application is someone managing employees, customers, operations, risk, growth, and reputation.
His approach is straightforward:
START WITH WHAT YOU ALREADY HAVE
A business can change significantly while its insurance stays exactly the same.
ONGOING BUSINESS SUPPORT
Customer Service & Retention Specialist | English & Spanish
Once Business Insurance is placed, ongoing service needs continue.
BASED IN KATY. SERVING TEXAS.
Echevarria Agency is based in Katy and serves eligible business owners throughout Texas.
Whether you operate locally or elsewhere in the state, the approach is the same:
Explore Business Insurance in Katy, TXA SIMPLE WAY TO START
What does your company do, where does it operate, and who are your customers?
Starting a company, contract requirement, customer request, renewal, growth, or existing-policy questions?
If you already have Business Insurance, we can begin with what you carry today.
Discuss available liability coverage, limits, deductibles where applicable, related commercial coverage, and recommendations.
Understand the limits, exclusions, and how General Liability fits with the rest of your Business Insurance.
COMMON QUESTIONS
General Liability Insurance is a core commercial liability coverage conversation for many businesses. Exact protection depends on the specific policy, limits, exclusions, endorsements, conditions, and carrier.
There is no universal answer for every business. Operations, customers, contracts, work locations, industry, existing insurance, and other circumstances can influence whether General Liability deserves consideration.
That depends on the business. General Liability focuses on certain liability exposures, while an eligible BOP may combine certain commercial coverages into a package.
Explore Business Owner’s Policy InsuranceThere is no single limit appropriate for every company. Contract requirements, business operations, liability exposures, available carrier limits, existing insurance, and other circumstances can all be relevant.
Business type, industry, years in operation, revenue, payroll, employees, claims history, location, limits, deductibles where applicable, and underwriting may affect pricing and eligibility.
No. Vehicles, property, employees, equipment, Workers’ Compensation, Commercial Umbrella, or other coverage may need separate conversations depending on the operation.
General Liability is commonly part of contract-related insurance conversations, but the actual contract requirements and policy should be reviewed rather than assuming any policy automatically satisfies a specific agreement.
Yes. We can start with your existing Business Insurance, discuss how the company has changed, and identify questions that deserve attention.
READY FOR ANOTHER LOOK?
Operations, contracts, customers, employees, and locations can change as your business grows. We can start with what you have now and help you understand the next step.
Prefer to talk? Call 281-697-6215.