Buildings + Business Property
Discuss eligible buildings, contents, equipment, inventory, and other physical property.
BUILT AROUND WHAT THE BUSINESS OWNS
Protecting the Physical Property Your Business Depends On
Your business may depend on much more than a building.
Equipment, inventory, furniture, computers, contents, machinery, and other physical property can represent years of investment.
Our Commercial Property Insurance conversations start with what your company owns, where that property is located, and what has changed as the business has grown.
Prefer to talk? Call 281-697-6215.
Discuss eligible buildings, contents, equipment, inventory, and other physical property.
Understand which property is being considered and what limits apply.
New equipment, inventory, locations, or property can create reasons to revisit existing coverage.
A locally based agency helping eligible businesses throughout Texas.
THE PROPERTY INSIDE MATTERS TOO
Commercial Property Insurance is not only a conversation for companies that own commercial real estate.
A business may lease its location and still own significant physical property inside it.
If the business owns an eligible commercial building, the structure may be part of the property insurance conversation.
A business can invest heavily in physical property even when it leases the building it operates from.
The better starting question is:
What physical property does the business depend on to operate?
UNDERSTAND THE PROPERTY
Different businesses depend on different physical assets.
Eligible commercial buildings may be part of the Commercial Property Insurance conversation depending on the policy and underwriting.
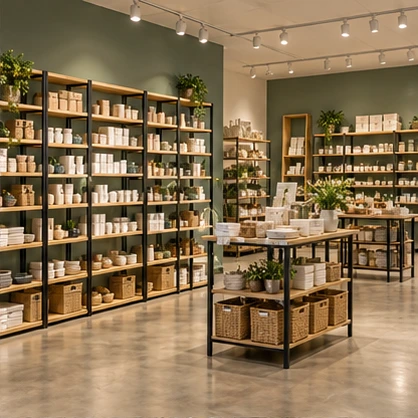
Physical items used to operate the business may represent a significant investment.
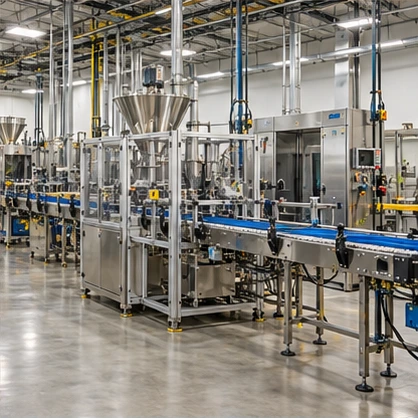
Equipment values can change as the company purchases, replaces, or upgrades physical assets.
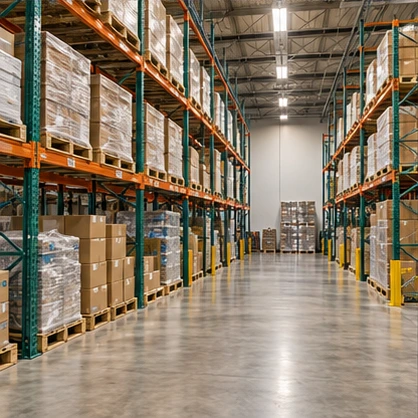
Inventory levels may grow significantly as the business expands.
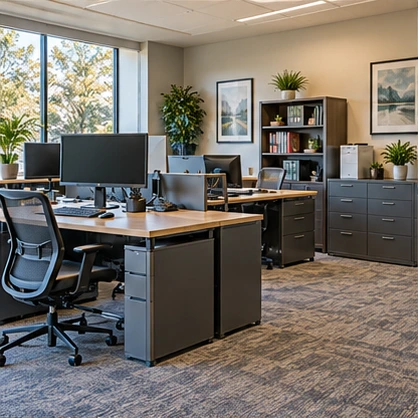
Physical business property can still be significant even when the company does not own heavy equipment or inventory.
Commercial Property Insurance should begin with identifying the property the business actually relies on.
WHEN THE PROPERTY CHANGES
The physical property a company owns today may look very different from what it owned when the current limits were selected.
UNDERSTAND THE BASICS
Commercial Property coverage should not be reduced to:
“I have property insurance.”
Commercial Property Insurance can address eligible physical business property subject to the actual policy’s terms, limits, exclusions, conditions, and endorsements.
Understand what property is being considered, what limit applies, and whether the amount still reflects the property the business owns today.
Where applicable, deductible choices can affect both premium and the responsibility retained by the business after certain eligible losses.
Policies can contain exclusions, limitations, conditions, and optional endorsements that deserve review.
Knowing that a Commercial Property policy exists is not the same as understanding what property and limits the policy actually addresses.
START WITH WHAT YOU OWN TODAY
Business property can accumulate gradually.
Those changes can add up.
The purpose of a review is not to assume the current limits are wrong.
It is to compare what the business owned then with what it owns now.
LEASING DOESN’T MEAN YOU OWN NOTHING
A landlord may own the structure itself.
A tenant business may still own significant physical property inside the leased space.
Do not assume:
“I don’t own the building, so Commercial Property Insurance does not apply to me.”
Tell us what the business owns and what the lease requires.
UNDERSTAND THE DIFFERENCE
Focuses on eligible physical business property subject to the specific policy.
A BOP may combine certain property and liability coverage into one policy structure for eligible small and midsize businesses.
The right conversation depends on the business, property, liability needs, carrier eligibility, and underwriting.
Explore Business Owner’s Policy InsuranceWHEN PROPERTY MOVES
Contractors can own substantial business property.
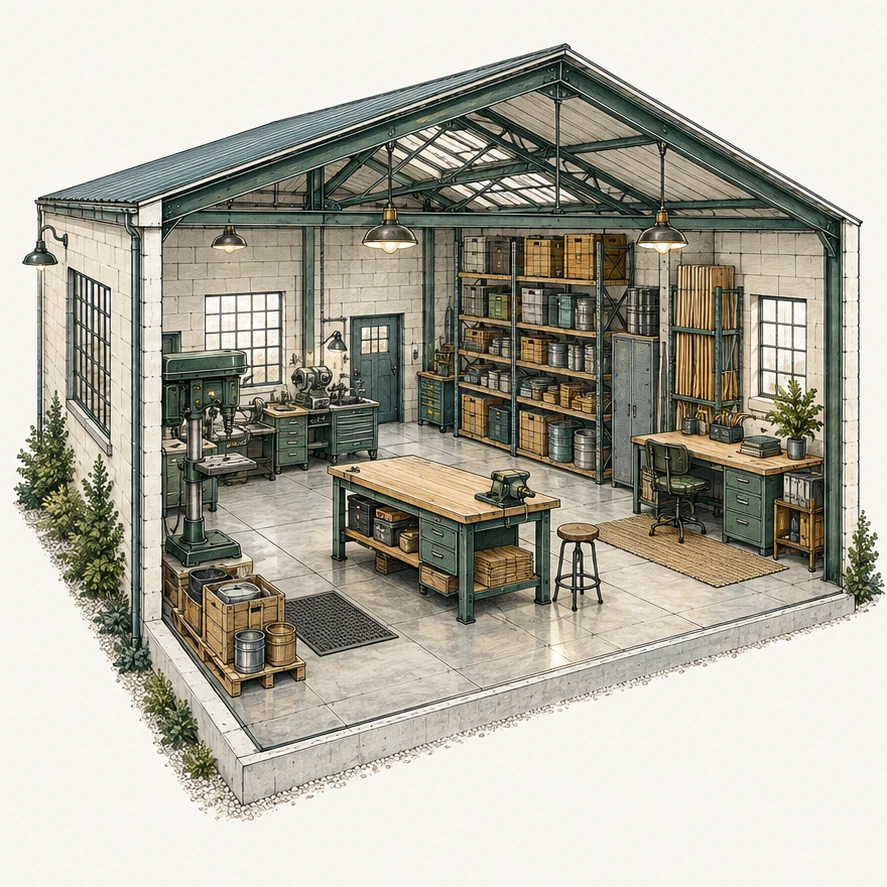
Commercial Property Insurance may be relevant for eligible shops, offices, buildings, contents, and fixed business property.
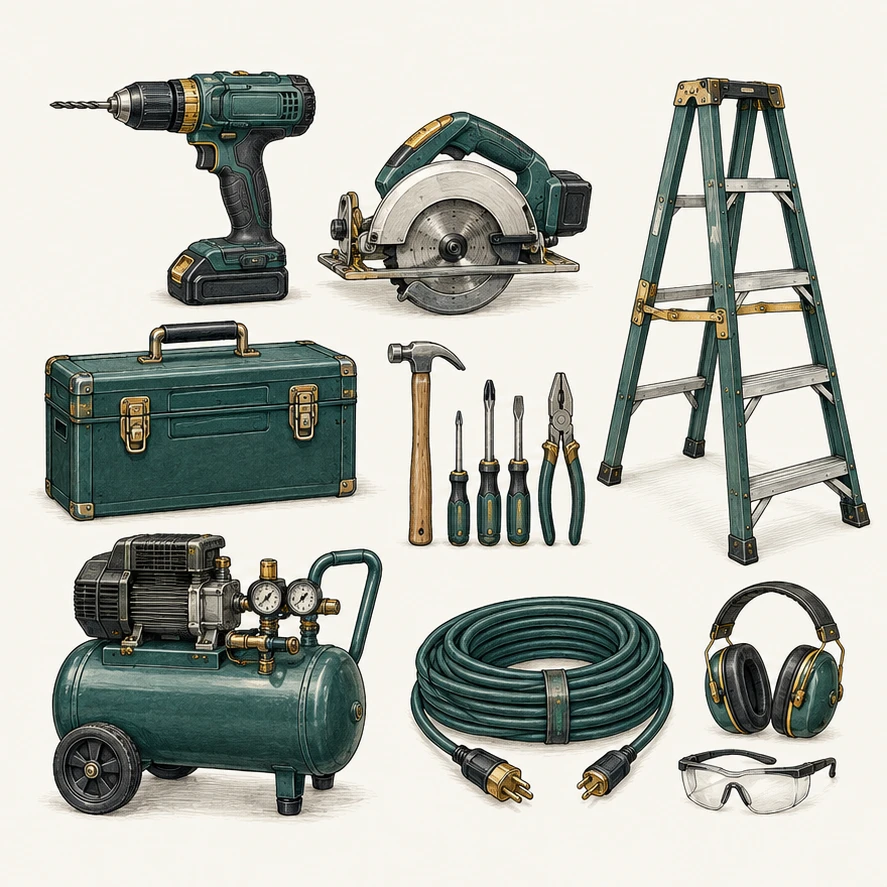
Do not automatically assume Commercial Property Insurance protects every tool or piece of equipment everywhere it travels.
DIFFERENT BUSINESSES. DIFFERENT PROPERTY.
WHAT CAN AFFECT THE PRICE?
There is no universal Commercial Property Insurance price for every business.
A useful Commercial Property quote requires more than a business address.
It requires understanding what property the company has and how the business operates.
KEEP PROPERTY INFORMATION CURRENT
Property values can grow as equipment, inventory, and other assets accumulate.
New equipment, inventory, locations, or contents can change the property picture.
Different property, locations, and uses can be treated differently under insurance policies.
Vehicles, liability, employees, contracts, and other exposures may require separate or related conversations.
Personal and Business Insurance serve different purposes.
SERVICE AFTER THE SALE
BASED IN KATY. SERVING TEXAS.
Echevarria Agency is based in Katy and helps eligible businesses throughout Texas explore Commercial Property Insurance.
The starting question stays the same:
What property does the business own and depend on?
Explore Business Insurance in Katy, TX
A SIMPLE WAY TO START
What does the company do and where does it operate?
Building, contents, equipment, inventory, or other business-owned physical property?
Already insured? Start with the policy and limits you have now.
Discuss available property coverage, limits, deductibles, and related commercial options.
Understand what property is being considered and how the available options work.
COMMON QUESTIONS
Commercial Property Insurance can provide coverage for eligible physical business property subject to the specific policy’s terms, limits, exclusions, conditions, deductibles, and endorsements.
Available property coverage depends on the business, carrier, and policy. Buildings, eligible business contents, equipment, inventory, and other physical business property may be part of the conversation.
Possibly. A business may lease the building while owning equipment, inventory, furniture, computers, or other property inside the location.
There is no universal limit for every company. Property values, inventory, equipment, location, available carrier limits, and underwriting can all affect the conversation.
Business type, industry, location, property values, claims history, selected limits, deductibles, operations, and carrier underwriting may affect eligibility and pricing.
Commercial Property focuses on eligible business property. A BOP may package certain property and liability coverage for eligible businesses.
Explore Business Owner’s Policy InsuranceDo not assume they are covered in every location or circumstance. Property that moves between shops, vehicles, and job sites may require a separate tools/equipment or Inland Marine conversation.
Explore Contractor InsuranceYes. We can begin with your existing policy and discuss current property, limits, equipment, inventory, location changes, and other business changes.
READY FOR ANOTHER LOOK?
Buildings, equipment, inventory, contents, and locations can change as a company grows. We can start with what you have now.
Prefer to talk? Call 281-697-6215.