Business Vehicle Coverage
Insurance conversations built around eligible vehicles used in business operations.
BUILT AROUND THE BUSINESS
Your business vehicles are more than transportation.
They may carry employees, tools, equipment, materials, or the work your company depends on every day.
Whether you operate one company vehicle or a growing fleet, our Commercial Auto Insurance conversations start with how the vehicles are owned, driven, and actually used in the business.
Prefer to talk? Call 281-697-6215.
Insurance conversations built around eligible vehicles used in business operations.
Understand why who drives and how vehicles are used can affect the insurance process.
Commercial Auto questions can begin with one company vehicle or an expanding fleet.
A locally led insurance agency helping business owners throughout the state.
START WITH HOW THE VEHICLE IS USED
This is one of the most common questions business owners ask.
The answer depends on the vehicle, ownership, use, driver, policy terms, and carrier requirements.
Personal Auto Insurance is generally designed around eligible personal ownership and use.
Business ownership, employees driving, job-site travel, transporting tools or equipment, deliveries, and other business activity can materially change the insurance conversation.
Do not automatically assume a Personal Auto policy addresses every type of business vehicle use.
The better question is:
How is the vehicle actually being used?
COMMERCIAL DOESN’T HAVE TO MEAN LARGE
You do not need a large fleet before business vehicle use deserves attention.
The useful question is not:
“Do I have enough vehicles to be a commercial account?”
It is:
“How is this vehicle used in my business?”
WHEN THE OPERATION CHANGES
Commercial Auto Insurance should have an opportunity to change as the business changes.
Moving from personal transportation to a dedicated company vehicle can create new insurance questions.
The insurance should reflect the vehicles the company actually operates.
New drivers can affect eligibility, underwriting, and the overall Commercial Auto picture.
More vehicles and drivers can create more information that needs to remain current.
Customers or other organizations may create additional insurance requirements.
A vehicle used occasionally may later become a full-time service vehicle.
UNDERSTAND THE COVERAGE
Available coverage depends on the vehicle, business, drivers, carrier, underwriting, and policy selected.
May address certain eligible bodily injury or property damage liability arising from covered vehicle use, subject to policy terms and limits.
May help address certain covered physical damage to an insured vehicle resulting from a collision, subject to policy terms and deductible.
May address certain eligible non-collision physical damage losses, subject to the policy’s terms, exclusions, and deductible.
May be available depending on the carrier, product, jurisdiction, and selected options.
May be available depending on the product, carrier, eligibility, and policy terms.
Business owners should understand both the limits selected and the deductibles that may apply.
Having Commercial Auto Insurance is not the same as understanding what the policy includes.
WHEN THE BUSINESS USES VEHICLES IT DOESN’T OWN
A business does not always own every vehicle used in connection with its operations.
Hired and Non-Owned Auto coverage may be relevant in certain situations depending on the business, vehicles, drivers, carrier, and policy terms.
Not every rented, borrowed, leased, or employee-owned vehicle automatically qualifies.
The actual use and policy terms must be reviewed.
BUSINESS VEHICLES SHOW UP IN MANY INDUSTRIES
Trucks, vans, service vehicles, tools, equipment, and job-site travel.
Explore Contractor Insurance
Technicians traveling between customer locations with parts and equipment.
Service vans and work trucks supporting daily operations.
Vehicles used to reach homes, businesses, and job sites.
Vehicles carrying employees, tools, supplies, or equipment.
Vehicles used for deliveries, errands, or operational needs.
Company vehicles or employees driving as part of business activity.
Multiple vehicles, drivers, additions, removals, and changing operations.
A STRONG CONNECTION
Contractors often depend on vehicles to perform the work itself.
Vehicles may be used to:
Commercial Auto may be one part of a broader Contractor Insurance conversation involving liability, property, tools and equipment, Workers’ Compensation considerations, and other commercial risks.
Explore Contractor Insurance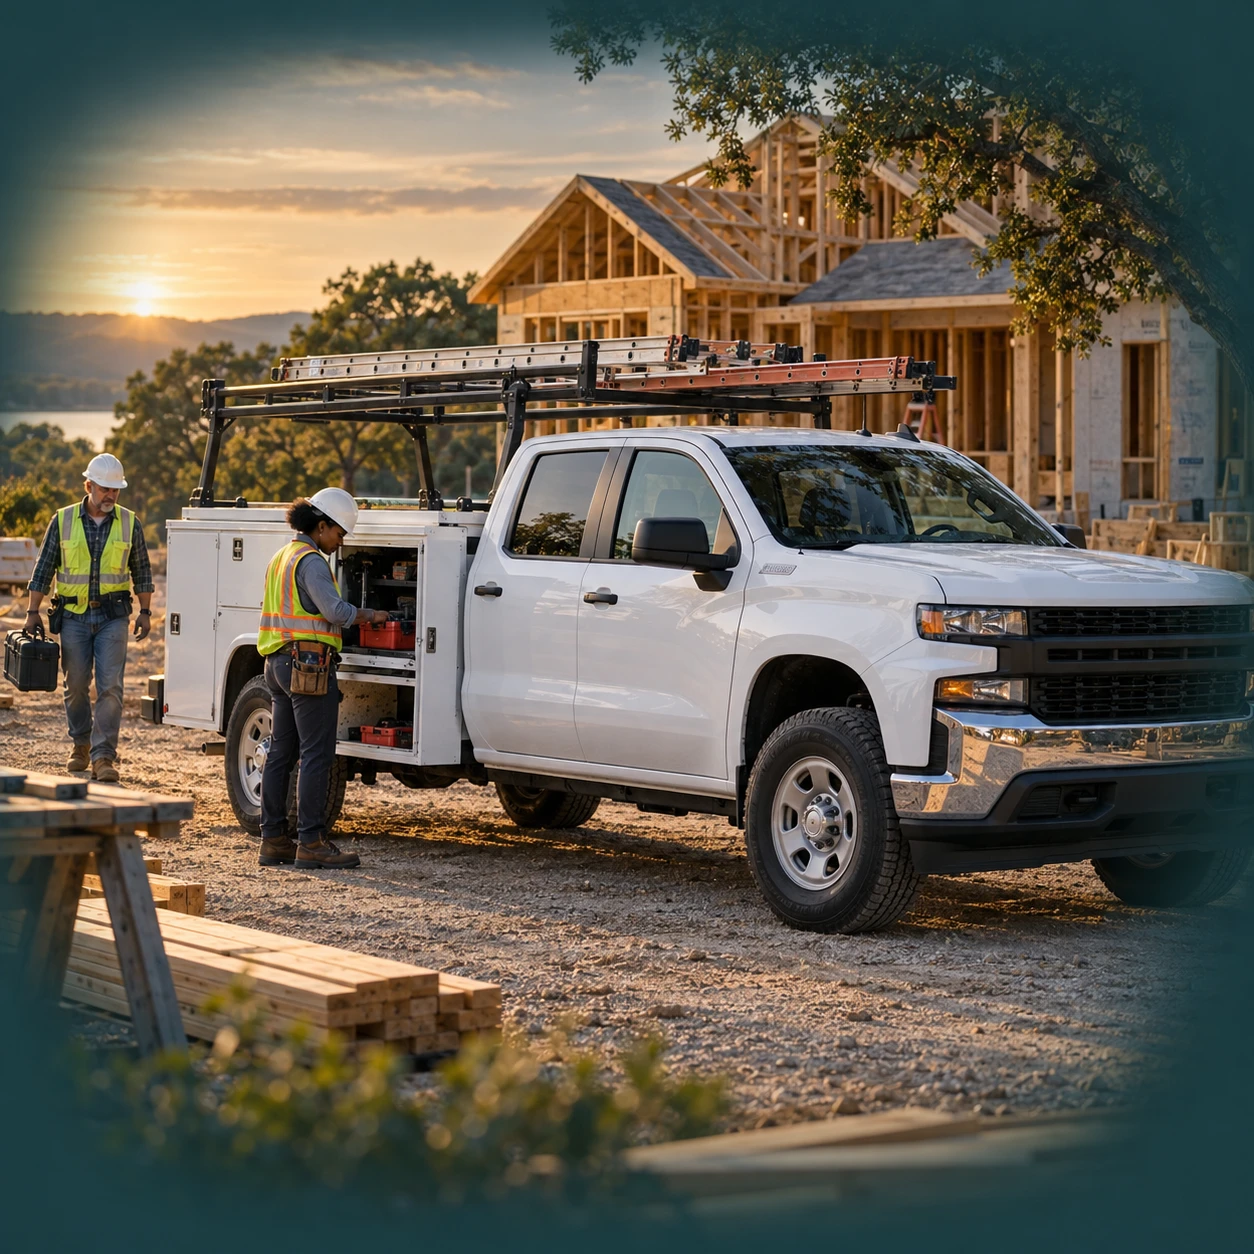
KEEP THE POLICY CURRENT WITH THE OPERATION
Business use can materially change the insurance conversation.
Vehicles are bought, sold, replaced, and added as businesses grow.
Employees and driver responsibilities change over time.
Know what limits the business is carrying and why.
New services, vehicles, employees, contracts, and territories can create reasons to revisit Commercial Auto Insurance.
WHAT CAN AFFECT THE PRICE?
There is no universal Commercial Auto Insurance rate for every business.
An accurate Commercial Auto quote considers more than the vehicle.
The business behind it matters too.Different vehicles can create different underwriting considerations.
What the company actually does matters.
Driver records may affect underwriting and premium.
Previous losses may be considered.
How often and why the vehicles are used can matter.
Where the company operates can affect underwriting.
The people operating the vehicles are part of the insurance picture.
Selected liability and other limits can affect premium.
Deductible choices may affect cost.
Final eligibility, pricing, coverage availability, and approval depend on the applicable carrier.
START WITH WHAT YOU ALREADY HAVE
You do not need to wait until you are ready to switch carriers before asking questions.
Added, sold, or replaced vehicles.
Hired employees or changed regular drivers.
Vehicles are being used differently.
More vehicles or crews were added.
New agreements created insurance requirements.
Services, territories, or business activity changed.
A useful time to take another look.
You are unsure whether current liability limits still fit the operation.
The purpose of a review is not to assume your current insurance is wrong.
It is to make sure the current operation gets considered.
BUSINESS-OWNER EXPERIENCE
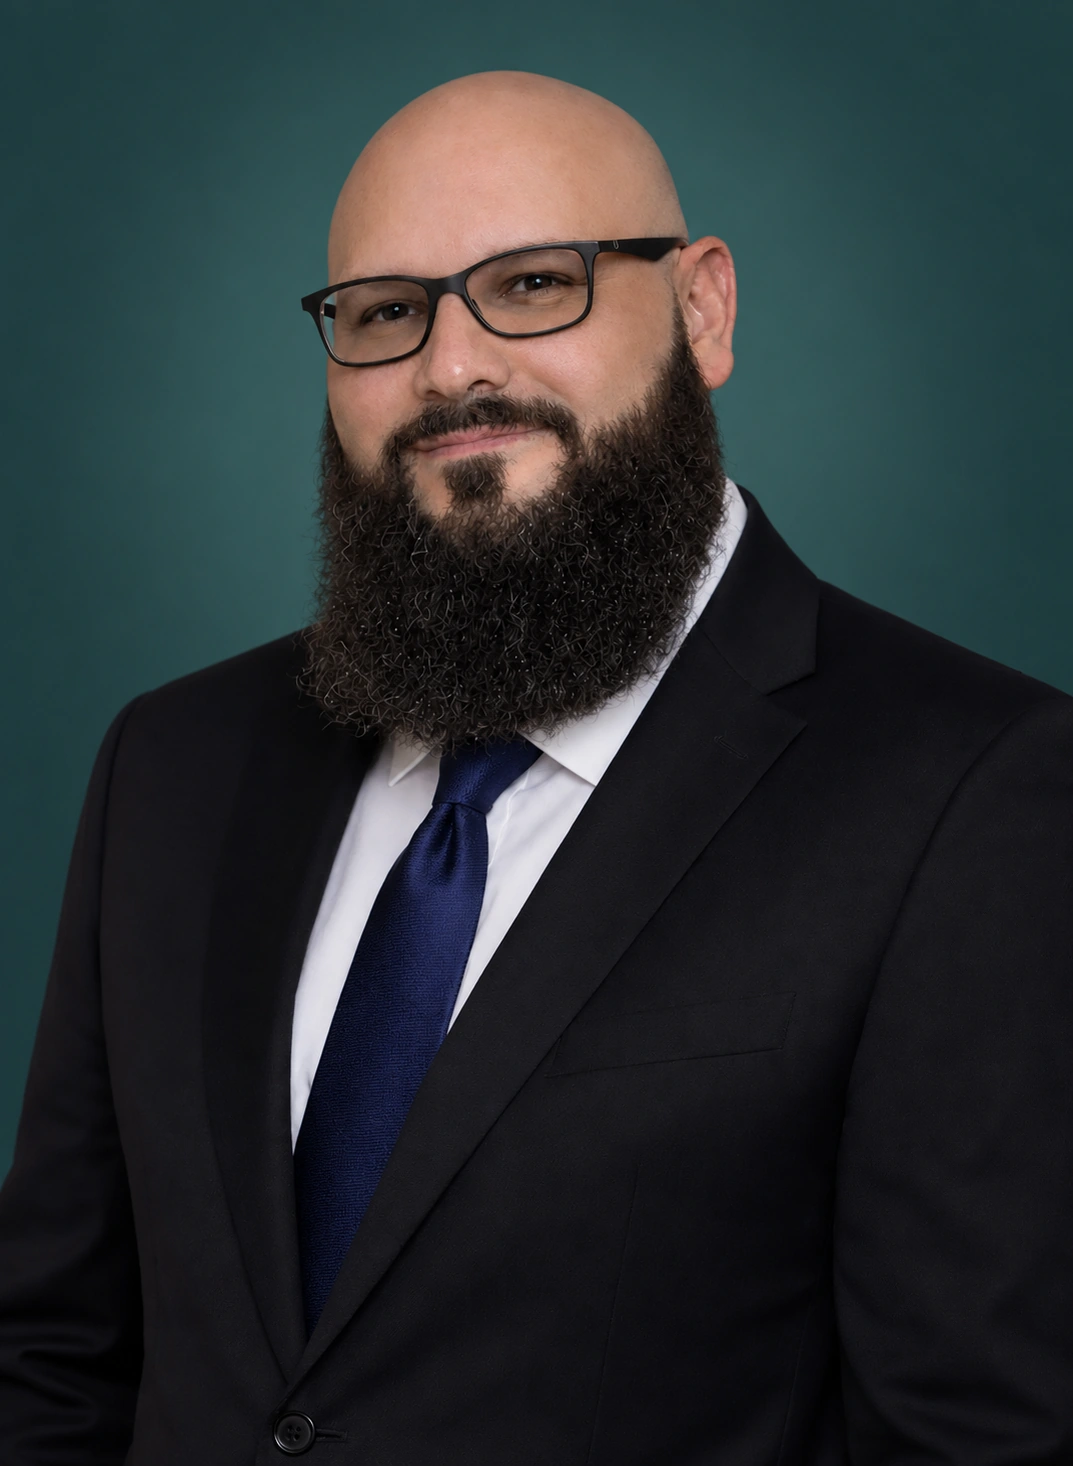
Agency Owner | Business Insurance & Operations
Francisco spent 15 years as a business owner in the trucking industry before helping lead Echevarria Agency.
He understands that business vehicles are not simply assets in a parking lot.
They may be how the company reaches customers, moves employees, transports equipment, and gets the work done.
How does your business depend on its vehicles?
That is where Francisco wants the Commercial Auto conversation to begin.
Meet Francisco EchevarriaVEHICLES ARE ONLY ONE PART OF THE BUSINESS
Workers’ Compensation and Commercial Umbrella may also deserve discussion depending on the business and available options.
ONGOING BUSINESS SUPPORT
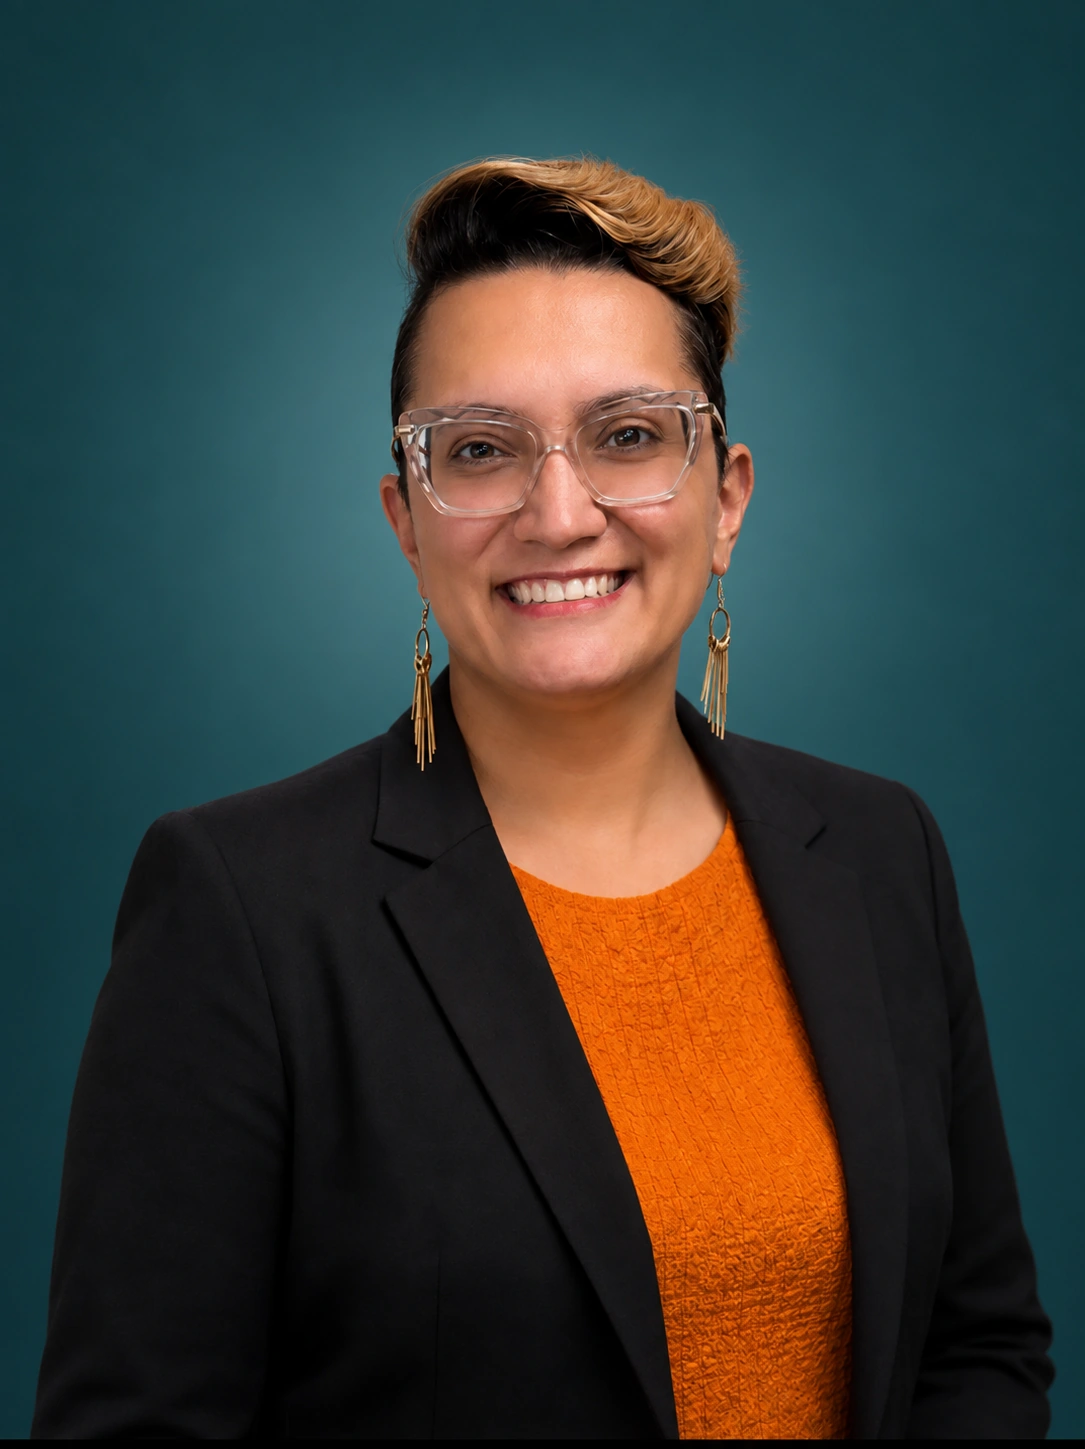
Customer Service & Retention Specialist | English & Spanish
Commercial Auto accounts often need ongoing service after a policy is placed.
BASED IN KATY. SERVING TEXAS.
Echevarria Agency is based in Katy and serves eligible business owners throughout Texas.
Commercial Auto Insurance can be relevant to a company with one vehicle or many.
A contractor. A service company. A retailer. A restaurant. A professional business. A growing company operating across Texas.
The starting point stays the same:
Tell us how the business uses its vehicles.
A SIMPLE WAY TO START
What does the company do, where does it operate, and what has changed?
What does the business own, lease, or use, and how are those vehicles used?
Owners, employees, regular drivers, and new hires may all be relevant.
Discuss liability, physical damage, limits, deductibles, Hired and Non-Owned Auto where applicable, and other available options.
Understand what you are considering before deciding how to proceed.
COMMON QUESTIONS
It depends on how vehicles are owned and used in connection with the business, along with applicable policy terms and carrier requirements. If a vehicle is used for business activity, it is worth discussing rather than assuming Personal Auto Insurance applies.
Do not automatically assume that you can. Business use can materially change the insurance conversation, and actual coverage depends on the policy, ownership, vehicle use, drivers, carrier, and underwriting.
Eligible vehicle types vary by carrier and business. Commercial Auto may include certain work trucks, vans, passenger vehicles, company cars, fleet vehicles, and other eligible business vehicles.
Driver eligibility depends on the policy and carrier requirements. Owners, employees, and other drivers may need to be reviewed, listed, or approved.
Available coverage can include liability, collision, comprehensive, Uninsured or Underinsured Motorist coverage, Medical Payments, Hired and Non-Owned Auto where applicable, and other options depending on the carrier and policy.
Hired and Non-Owned Auto coverage may be relevant when a business uses certain vehicles it does not own. Exact eligibility and coverage depend on the policy, vehicle use, drivers, and circumstances.
Vehicle type, business operations, driving history, claims history, vehicle use, business location, covered drivers, limits, deductibles, and carrier underwriting can all affect pricing and eligibility.
Yes. We can begin with your existing insurance, current vehicles, drivers, business use, limits, and recent operational changes.
READY FOR ANOTHER LOOK?
Vehicles, drivers, contracts, and operations can change as your business grows. We can start with what you have now and help you understand the next step.
Prefer to talk? Call 281-697-6215.